Trading Bitcoin Volatility on Hyperliquid: BVIV Perps Explained
By CMM Team - 21-Sep-2026
Trading Bitcoin Volatility on Hyperliquid: BVIV Perps Explained
You can now trade Bitcoin's fear gauge on Hyperliquid. The BVIV perpetual, a contract that tracks the Volmex Bitcoin Implied Volatility Index, went live today through Markets by Kinetiq. It gives on-chain traders something they've never had before on Hyperliquid: a direct way to go long or short on the magnitude of Bitcoin's price swings, without taking a directional bet on where BTC goes next.
If you've ever wished you could profit from a stretch of high volatility without needing to pick a direction, or hedge your spot book against a sudden calm, this is the instrument. Below, we'll break down exactly how it works, who built it, and what it means for your trading toolkit on Hyperliquid.
What Is the BVIV Index?
BVIV stands for the Bitcoin Volmex Implied Volatility Index. Think of it as the crypto equivalent of Cboe's VIX, which tracks 30-day implied volatility on the S&P 500. The BVIV measures the market's expectation for how much Bitcoin will move over the next 30 days, derived from real-time call and put option quotes across leading derivatives venues.
When Bitcoin options traders price in larger potential swings, BVIV rises. When the market expects relative calm, BVIV drops. That single number becomes a tradable summary of the market's collective anxiety, or composure, about Bitcoin's near-term trajectory.
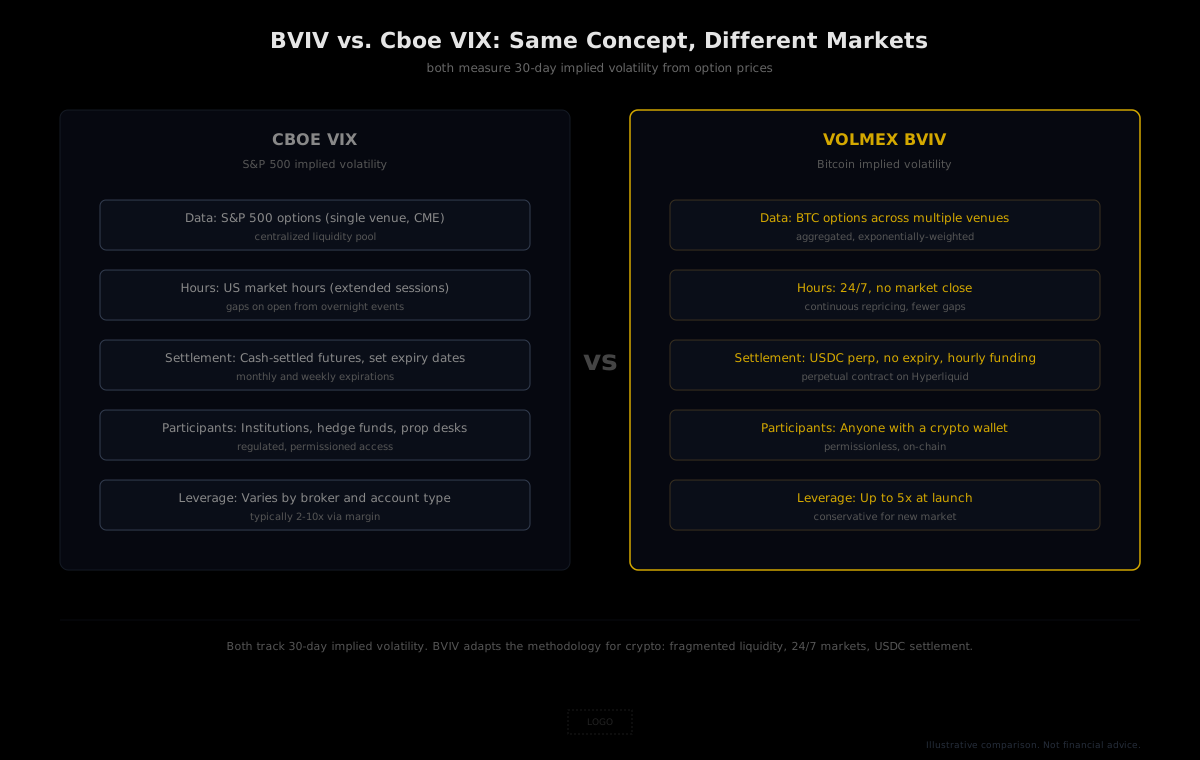
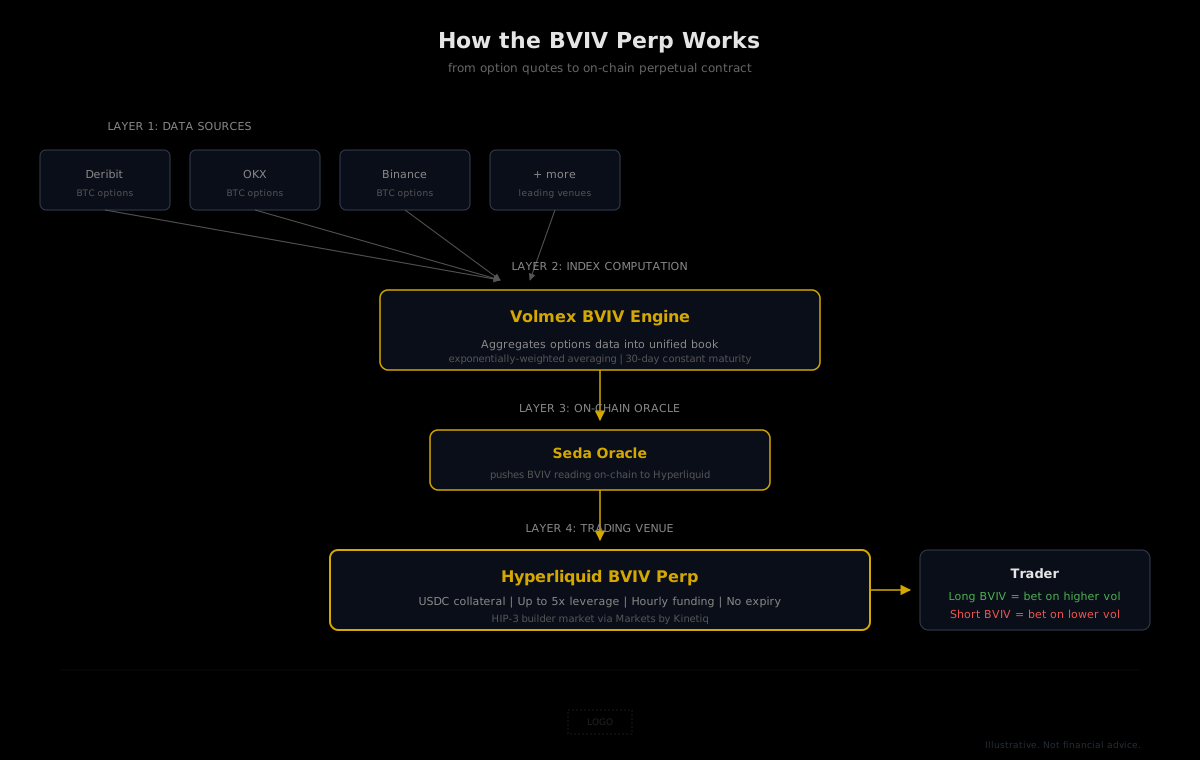
The index methodology mirrors established volatility index construction adapted for crypto's structural realities: fragmented liquidity across venues, 24/7 settlement cycles, and venue-specific funding mechanics. Volmex consolidates option and futures data from leading exchanges into a unified option book, then applies exponentially-weighted averaging to smooth the output into a single real-time figure.
How the BVIV Perp Works on Hyperliquid
The BVIV perpetual contract was deployed as an HIP-3 builder market, the same standard that powers Hyperliquid's equities, commodities, and index perps. Markets by Kinetiq led the listing alongside Volmex and Perps.fun, making this the first on-chain perpetual futures market for the Volmex Bitcoin volatility index.
The contract is collateralized and denominated in USDC, with up to 5x leverage available at launch. Seda's oracle infrastructure feeds the Volmex index reading directly on-chain, which means the perp price tracks the live BVIV value in real time. Like other Hyperliquid perpetuals, funding rates apply hourly, and the contract settles continuously with no expiry date.
Cole Kennelly, founder and CEO of Volmex Labs, described the launch as "a convenient tool for volatility hedging and speculation" for crypto traders. The key advantage over options: you don't need derivative expertise or the capital overhead of managing gamma, theta, and vega through complex option structures. You simply go long volatility or short volatility.
Why Volatility Perps Matter
Most crypto traders express views on direction. You think BTC goes up, you go long. You think it goes down, you short. But there's a third dimension that directional traders often overlook: volatility itself.
Volatility tends to be persistent and mean-reverting. When implied volatility is elevated, it often reverts toward its historical average over time. When it's suppressed, catalysts tend to snap it back up. These patterns create trading opportunities that have nothing to do with whether BTC is headed for new highs or a correction.
Practical Use Cases
- Hedging a spot portfolio: If you hold BTC and want protection against a volatility spike (which typically correlates with sharp drawdowns), going long the BVIV perp adds a hedge that pays off when fear rises, regardless of whether you got the direction right.
- Volatility mean-reversion trades: When BVIV is at the extremes of its range, traders can fade the move by going short during implied-vol spikes or long during compressed-vol environments, expecting a reversion.
- Event hedging: Before known catalysts like FOMC meetings, CPI releases, or major protocol upgrades, implied volatility tends to rise. A long BVIV position captures that expansion without committing to a directional bet on the event outcome.
- Vega isolation: Options traders who want pure volatility exposure without delta, gamma, or theta complications can use the BVIV perp as a cleaner instrument. One position, one payoff dimension.
Where BVIV Fits in Hyperliquid's Growing Product Map
Hyperliquid lists 286 tradeable perpetual markets as of today: 178 native crypto perpetuals settled on the Hyperliquid L1 order book, and 108 HIP-3 builder markets deployed primarily by trade.xyz, covering equities, commodities, indices, and forex.
The BVIV perp adds a new asset class to that roster: volatility indices. It sits alongside equities like TSLA and AAPL perps, commodities like gold and oil, and traditional market indices, giving Hyperliquid one of the broadest on-chain product suites in DeFi. What started as a crypto-native perp exchange has evolved into something closer to a full-spectrum derivatives venue.
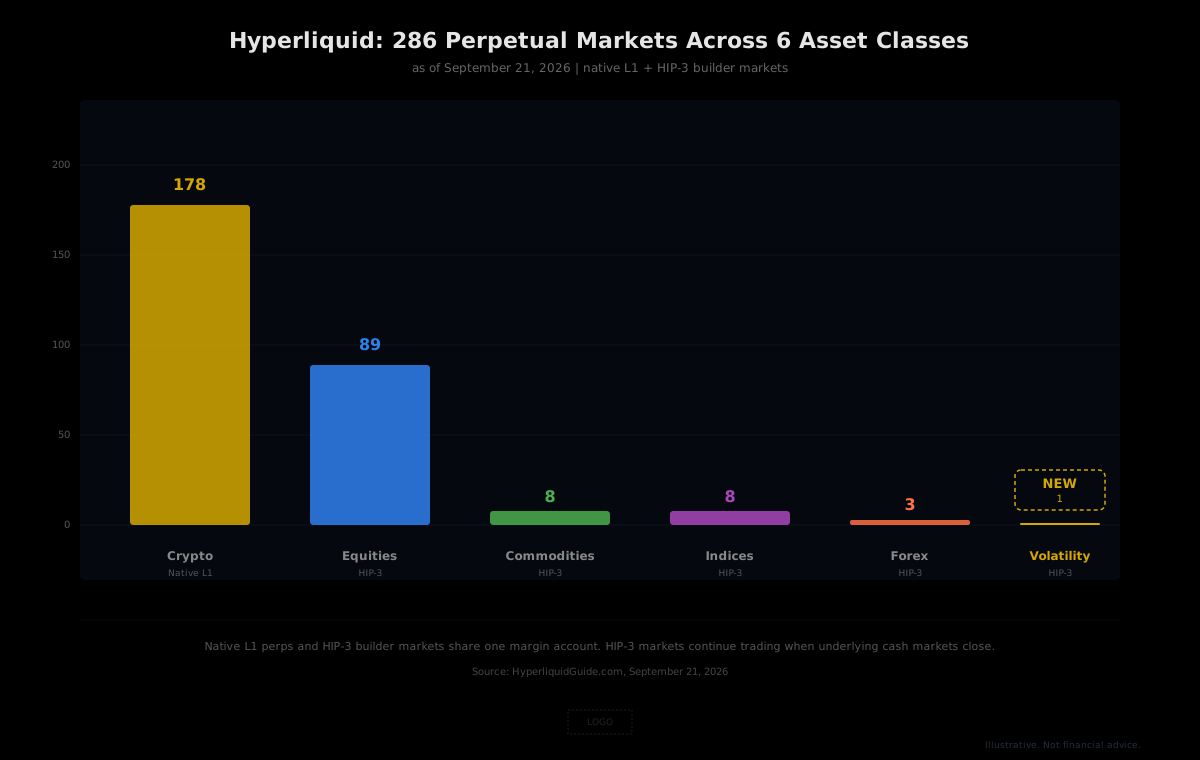
| Asset class | Markets | Venue | | --- | --- | --- | | Crypto | 178 | Native Hyperliquid perps | | Equities | 89 | HIP-3 via trade.xyz | | Commodities | 8 | HIP-3 via trade.xyz | | Indices | 8 | HIP-3 via trade.xyz | | Forex | 3 | HIP-3 via trade.xyz | | Volatility (NEW) | 1 (BVIV) | HIP-3 via Markets by Kinetiq |
BVIV vs. Traditional VIX: Key Differences
The analogy to Cboe's VIX is useful, but crypto volatility has structural differences worth understanding before you trade it.
| Dimension | Cboe VIX | Volmex BVIV | | --- | --- | --- | | Underlying | S&P 500 options | BTC options across venues | | Measurement window | 30-day implied vol | 30-day implied vol | | Trading hours | US market hours (extended) | 24/7, no market close | | Settlement | Cash-settled futures, set expiry | USDC perp, no expiry, hourly funding | | Liquidity sources | Centralized (CME) | Aggregated from multiple crypto option venues | | Leverage | Varies by broker | Up to 5x at launch on Hyperliquid |
The 24/7 trading schedule is particularly relevant for volatility products. Traditional VIX futures gap on open because overnight events reprice options while the market is closed. BVIV reprices continuously, which means fewer gaps and more opportunities to manage positions around catalysts in real time. However, crypto's fragmented options liquidity across exchanges introduces its own source of noise, which the Volmex methodology smooths through exponentially-weighted averaging.
Trading Considerations and Risk
Volatility products behave differently from directional assets, and the BVIV perp is no exception. Before you size up a position, here are the dynamics to keep in mind.
Contango and backwardation. Like traditional VIX products, the BVIV perp's funding rate reflects the market's term structure of volatility expectations. When traders expect volatility to be higher in the future, long positions pay funding (contango). When the market expects volatility to decline, shorts pay. Funding rates directly affect the carry cost of holding a position over time.
Mean reversion speed. Bitcoin implied volatility tends to mean-revert, but the speed varies. After a sudden spike caused by a liquidation cascade or macro shock, BVIV might snap back quickly. During a slow grind of declining realized volatility, the reversion can take weeks. Timing matters more than direction for many volatility trades.
Leverage limits. The 5x leverage cap at launch is conservative relative to Hyperliquid's crypto perps, and for good reason. Volatility products can make sharp percentage moves in short periods, so lower leverage reduces the risk of cascading liquidations in a new market with developing liquidity.
Liquidity depth. This is a new listing. Spreads will likely be wider and order book depth thinner than established crypto perps. Starting with smaller position sizes and wider stops makes sense until the market matures and more liquidity providers enter.
Key takeaway: BVIV perps are a powerful tool, but they trade differently from directional perps. The payoff is tied to how much the market moves, irrespective of direction. If you're used to going "long BTC," going "long BVIV" requires a fundamentally different mental model.
How HyperTracker Helps You Monitor Volatility Shifts
Volatility doesn't spike randomly. It correlates with identifiable on-chain behavior patterns. When large, profitable wallets start reducing exposure, implied volatility tends to rise shortly after as the market adjusts to the positioning shift. When smart money re-enters aggressively, volatility often compresses as conviction stabilizes the market.
HyperTracker's cohort analytics classify every wallet on Hyperliquid into 16 behavioral segments: 8 by position size (from Shrimp wallets under $250 to Leviathans above $5M) and 8 by all-time PnL (from Money Printers with over $1M in lifetime profit to Giga-Rekt wallets deep in the red). Tracking aggregate positioning across these cohorts gives you a leading indicator for when volatility regimes might shift.
For example, if Money Printer and Smart Money cohorts start unwinding long positions while Leviathan wallets reduce their gross exposure, that's a signal worth watching before entering a long BVIV trade. Conversely, if high-conviction cohorts are steadily accumulating with tight directional bias, volatility compression may be the higher-probability outcome.
Track Cohort Positioning Before Your Volatility Trade
HyperTracker gives you the intelligence layer: 16 behavioral cohorts, order flow snapshots, and smart money tracking across every asset on Hyperliquid. Use cohort signals to time your BVIV entries with more conviction.
With 286 perpetual markets now spanning crypto, equities, commodities, forex, indices, and volatility, Hyperliquid's product breadth is accelerating faster than most traders realize. BVIV perps won't be the last new asset class to land. But they might be the most misunderstood by traders who've never traded volatility as a standalone instrument.
Learn the mechanics. Start small. And use cohort data to build conviction before sizing up. That's how you turn a new instrument into an edge.